Understanding the language of commercial equipment financing is essential for making smart financial decisions. But let’s be honest—industry jargon can get overwhelming fast.
Whether you’re applying for your first equipment loan, considering leasing options, or just trying to make sense of financing documents, this guide is here to help. We’ve created a clear, straightforward dictionary of common commercial equipment financing terms—written with business owners and managers in mind.
If you have questions, remember that our team at Team Financial Group is just a phone call away. We specialize in fast, flexible equipment financing and love helping business owners feel confident about their options.
$1 Buyout Lease: A lease option that allows your business to purchase the equipment for a nominal fee—typically just $1—at the end of the lease term. This type of lease acts similarly to a loan, with predictable monthly payments, and is ideal if you plan to own the equipment long-term.
Learn more or apply for a $1 buyout lease on our financing page or this blog post.
Accounts Payable: The money your business owes to vendors, suppliers, or service providers. This is listed as a current liability on your balance sheet.
Accounts Receivable: The money owed to your business by customers or clients for goods or services delivered but not yet paid for. It’s considered a current asset.
Amortized Loan: A loan that is paid off through regular monthly payments over a set term. Each payment includes both interest and principal, with early payments being interest-heavy and later ones focused more on reducing the principal.
APR (Annual Percentage Rate): The total yearly cost of borrowing, expressed as a percentage. It includes the interest rate plus any additional fees or costs associated with the loan.
B
Balloon Payment: A large, lump-sum payment due at the end of a loan term. Common in structured financing, it can help lower monthly payments but requires planning for a big payoff at maturity.
Business Credit Score: A score ranging from 0 to 100 that reflects your business’s creditworthiness. A higher score can result in better financing terms and faster approvals.
C
Cash Flow Statement: A financial report showing the money coming in and going out of your business. It includes operating income, expenses, financing costs, and investments—critical for assessing your ability to repay a loan.
Collateral: Assets pledged to a lender to secure financing. If you default, the lender may seize the collateral to recover losses.
Capital Lease: Another term for a lease that functions like a purchase, typically with a $1 buyout option. The lessee assumes the risks and benefits of ownership.
D
Debt Service Coverage Ratio (DSCR): A financial metric that compares your available cash flow to your debt obligations. A DSCR above 1 means your business generates enough income to cover its debt payments.
Depreciable Assets: Business assets that lose value over time and can be depreciated for tax purposes. Examples include equipment, vehicles, and machinery.
Down Payment: An upfront payment made toward the total cost of a loan or lease. Many equipment loans offer 100% financing, so down payments may not be required.
E
Equipment Financing Agreement (EFA): A type of loan that gives you full ownership of the equipment from the start. You make fixed monthly payments over time until the loan is paid in full.
Equipment Leasing: A rental agreement for equipment use. You don’t own the equipment, but you gain access for a set period, often with lower monthly payments and options to renew or buy at lease-end.
RELATED: What Happens When an Equipment Finance Lease Expires?
Equity: The value of ownership in your business or an asset after subtracting any liabilities or loans. A healthy equity position can help secure better financing.
F
Fair Market Value (FMV) Lease: A lease where, at the end of the term, you can purchase the equipment at its estimated fair market value, continue leasing, or return it. This option is often ideal if you plan to upgrade equipment frequently.
Learn more about and apply for an FMV lease on our financing page.
Financing Statement (UCC-1): A public record filed by a lender to indicate their interest in financed property. This protects their legal rights in case of default.
Five Cs of Credit: Lenders consider five factors when evaluating financing applications:
Fixed Interest Rate: An interest rate that remains constant throughout the term of your loan or lease, ensuring predictable monthly payments.
G
Guarantee (Personal or Corporate): A promise by an individual or business entity to repay the loan if the borrower defaults. Personal guarantees are common for small business financing.
I
Independent Lenders: Financing providers that are not affiliated with traditional banks. They often offer more personalized service, faster approvals, and greater flexibility—like Team Financial Group.
Insolvency: When your business can’t pay its debts as they come due. Lenders may look at solvency ratios when assessing risk.
Interest Rate: The percentage of the loan amount charged by the lender for borrowing money. It can be fixed or variable.
L
Leaseback (Sale-Leaseback): A financing option where you sell your owned equipment to a lender and lease it back. This allows you to free up working capital without interrupting business operations.
Lien: A legal claim a lender places on financed property. It remains in effect until the debt is paid off.
Loan-to-Value (LTV) Ratio: The percentage of the asset’s value covered by the loan. In equipment financing, LTV can be up to 100%, meaning no down payment is required.
Long-Term Debt: Debt obligations that are scheduled to be paid over a period longer than 12 months.
M
Maintenance Agreement: A contract covering the upkeep and service of leased equipment. Often included in lease agreements for high-tech or specialized equipment.
Maturity: The end of the loan or lease term, when all scheduled payments are complete and ownership (if applicable) transfers or ends.
N
Non-Amortized Loan: A loan where principal isn’t paid off gradually. Instead, you may make interest-only payments with the full principal due at the end (see “Balloon Payment”).
Net Operating Income (NOI): Revenue from your business operations minus expenses (excluding financing costs). Used to assess your ability to support debt.
O
Operating Lease: A short-term lease where the equipment is returned at the end of the term. You don’t build equity, but payments may be lower and it keeps the asset off your balance sheet.
RELATED: What’s the Difference Between a Capital and Operating Lease
P
Principal: The original amount borrowed, excluding interest and fees.
Private-Party Sale: A purchase made directly from an individual or business rather than a dealership or vendor. Some lenders, including Team Financial Group, offer financing for private-party equipment sales.
R
Refinancing: The process of replacing an existing loan with a new one, often to get better terms, lower monthly payments, or extend the repayment period.
Residual Value: The estimated value of leased equipment at the end of the lease term. This influences buyout options and monthly payments.
Risk Assessment: The evaluation of your business’s ability to repay the financing. Includes credit history, industry trends, financial ratios, and cash flow analysis.
S
Section 179 Deduction: A tax benefit that allows you to immediately expense the full cost of qualifying equipment or vehicles (up to the IRS limit) instead of depreciating over several years. Especially valuable for businesses looking to reduce taxable income and improve cash flow.
Secured Loan: A loan backed by collateral, such as equipment or other assets. Typically comes with lower interest rates due to reduced lender risk.
Short-Term Debt: Loans or obligations that must be paid within 12 months.
Step Payment Plan: Flexible financing structures where payment amounts adjust over time—either increasing (step-up) or decreasing (step-down)—to match cash flow patterns.
T
Term: The agreed-upon length of time for repaying a loan or lease, typically expressed in months or years.
Traditional Loan: A standard loan where the lender provides funds to purchase equipment, and you repay with fixed monthly installments of principal and interest.
U
Underwriting: The process lenders use to evaluate credit risk and determine whether to approve a financing application—and under what terms.
Unsecured Loan: A loan that does not require collateral. Usually comes with higher interest rates due to the higher risk for lenders.
V
Variable Interest Rate: An interest rate that can fluctuate over time based on market conditions or index rates. Your monthly payments may increase or decrease accordingly.
W
Working Capital: The amount of liquid assets your business has to cover daily operations. Calculated as current assets minus current liabilities.
At Team Financial Group, we help business owners across industries navigate equipment financing with ease. Whether you’re replacing outdated machinery, expanding operations, upgrading technology, or investing in vehicles, we’re here to provide fast and flexible financing solutions.
Apply now or contact us at 616-735-2393 to speak with a financing expert.
The content provided here is for informational purposes only. For personalized financial advice, please contact our commercial financing experts.
Tom and David Gregwer have spent years in the insurance business as agents for Farmers Insurance. But outside their day job, their ambitions land on the basketball court.
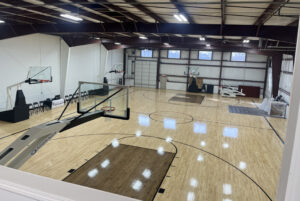
As avid sports enthusiasts involved in youth sports, Tom and David saw a need across the Grand Rapids area for more gym space that local volleyball and basketball clubs could use. This space could also be used by trainers and athletes who wanted to improve their games.
But they needed a little help to make their basketball dreams a reality.
Team Financial Group was happy to step in with financing for this project. Tom and David now have built two beautiful facilities in Wyoming and Kentwood that allow teams to practice, scrimmage, and train any time of the year. They’ve also established conference areas where coaches can record practice, view tapes, and meet with their teams.
These facilities can be conveniently rented for use via their HoopGNG app too.
We loved seeing this project get off the ground and are grateful to be a part of it.
You can learn more about Facility Rental by visiting www.hoopgng.com or by downloading the HoopGNG app.
Can Team Financial Help Your Business Dreams?
If you are looking for flexible and agile financing to help your business grow, then you’ve come to the right place. Team Financial Group has the expertise and experience to make sure you can reach your goals.
We offer many different financing options, often with same-day approval. To get started, give us a call at 616-735-2393 or fill out our short online contact form.
You might feel plenty busy dealing with today’s needs and challenges to place much thought into future planning. But investing time and resources into building a future-proof business strategy now can not only keep your organization sustainable but also reduce the number or severity of future issues.
Nobody can fully predict the future, but that doesn’t mean you can’t take practical steps to keep your business more agile, adaptive, and ready to capitalize on opportunities. This article will discuss what a “future-proof business” aims to accomplish and some potential considerations for a future-proof strategy.
Simply put, future-proofing is an attempt to analyze and respond to the types of changes that might lie ahead for your business. Once possible challenges and opportunities have been identified, you can then develop a plan for mitigating problems and getting the most returns from investments.
What kinds of changes should a business anticipate within a future-proofing strategy? There might always be surprises as times change, but general factors to evaluate include:
Isolating specific factors can be difficult, as each significantly influences the others. Economic trends and changing technology can affect the talent pool, for example. A change in the available workforce can inspire technological changes. It is all connected and worth evaluating broadly, particularly if you will need to explore financing options to enact future-proofing strategies.
Building a future-proof plan is less about establishing stepping stones and more about considering an overall trajectory. Your strategy should arc toward overall goals but remain capable of adjusting investments when necessary.
Here are some actions to consider as part of an overall future-proofing strategy:
Information fuels more confident decisions, and your business’s own data might be able to tell you a lot about what the future may have in store.
We have previously discussed data-informed decision making and building data-driven processes in regard to financing, but similar tactics can be used for building future-proof strategies as well. Gather data that can help identify strengths, weaknesses, and trends within your business, as well as keep a close eye on your finances.
More data is better, as long as that data is useful in targeting your goals. Collecting data simply for data’s sake can lead to more time sifting through numbers than taking actual action.
Speaking of time, automation is a trend that is often more likely to provide safe returns on productivity and resources.
Investments in certain technology, software, or equipment can step in for humans to handle repetitive tasks, freeing up time for more intricate work. However, be considerate in your automation choices. Which options are more likely to stand the test of time, and are the initial disruptions with integration worth the long-term results?
Automation and other system advances can be highly beneficial to your future productivity but can also cause obstacles and delays if they do not communicate effectively with each other.
A future-proof business should always consider how the different parts of a plan interact with each other before investing in them. Actions that are more compatible and consolidated will cause fewer disruptions and will often be easier to adjust if the need calls for it.
Human connectivity is also a critical part of integration. When considering changes, factor time into reviewing your employees’ needs and expectations with any systems they will interact with, as well as time helping them adjust to new tech and procedures.
As your business considers trends and shifting resources, you might see opportunities to expand products, services, or even the industries you cover.
If making such considerations, it’s important to evaluate what new or updated equipment your business might need to finance to expand. The more flexible and adaptable that equipment is, the better positioned your business may be to take advantage of change.
Whatever diversification options you consider, evaluate how they will hold up to your established brand and values. How might your identity evolve – if at all – as you progress and finance new initiatives?
When you are ready to act on a future-proof strategy, Team Financial Group can help you finance the equipment and technology to move you forward. Our flexible financing options can help keep you better prepared to pivot when the situation demands, as well.
Let’s discuss how we can help your business adapt and excel over time. Contact us or fill out our simple application form to get the ball rolling.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
Timing can make a huge difference when it comes to equipment purchases. Section 179 tax deductions can provide one potential savings opportunity, but you will want to act before the end of 2024 to reap the most benefit from it.
Section 179 might seem complex at first, but knowing its specifics can be rewarding. This article will outline what Section 179 is, who can qualify for deductions, and why future changes might make 2024 the best time to take advantage of it. You can also contact our equipment financing experts with questions or to ask about specific cases.
Section 179 of the IRS tax code provides more immediate incentives for businesses purchasing qualifying depreciable business equipment such as machinery, vehicles, office equipment, and software. Instead of following standard depreciation deductions over several years, the full purchase price of these items could be deducted for the current tax year.
The IRS caps Section 179 tax deductions at a maximum amount each year. For 2024, this maximum total is $1,220,000. However, bonus depreciation can be applied to a percentage of qualifying purchases beyond a total phase-out threshold of $3,050,000. Total qualifying purchases must be $4,270,000 or lower for all these benefits to apply.
This is where the timing comes in.
While the maximum deduction and phase-out threshold allowed through Section 179 have gradually increased from year to year, the bonus depreciation has decreased. Whereas bonus depreciation applied to 100% of qualifying costs in 2021, it applies to only 60% of qualifying costs in 2024.
Bonus depreciation is planned to decrease each consecutive year, with 40% in 2025, 20% in 2026, and ultimate elimination in 2027.
Let’s look at an example that might make this easier to understand. Say you purchased $2,000,000 in qualifying equipment in 2024. You could take $1,220,000 of that purchase as a full deduction. Of the remaining $780,000, 60% could be deducted for an extra $468,000 in deductions. The same bonus depreciation deduction in 2025 would only be 40% or $312,000 in deductions.
So, if your business’s equipment purchasing plans could take advantage of bonus depreciation, this year may be the most beneficial time to move forward with buying. If you do wait until 2025, however, you will still have some bonus depreciation to take advantage of, as well as a potential slight increase in the maximum deduction.
As with many regulations, there are certain restrictions as to what qualifies for Section 179 deductions and bonus depreciation. In addition to the maximum deduction and phase-out threshold amounts described above, equipment must also:
Outside of these factors, the scope of qualifying equipment is quite wide. Equipment that can be eligible for Section 179 tax deductions includes, but it is not limited to:
Your method of equipment financing might also affect eligibility. Many financing agreements and loans fall under eligibility, while many leasing options do not. It is best to speak with a financing expert or your tax advisor to determine what type of financing option might best suit your organization’s needs.
Do you want to make Section 179 part of your growth plans?
Section 179 tax deductions can serve as a helpful catalyst for longer-term business growth, putting pieces in place now that can pave the way for expansion later.
Our financing experts at Team Financial Group can help you put your plans into motion with financing solutions that meet your needs and help you qualify for additional benefits. Starting a conversation with us is as easy as calling us or filling out our simple online form.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
The road to sustainable business growth is paved with good incremental decisions. It is rare for a business to have all the resources needed to make all the improvements they want at one time. Many improvements require substantial financial investments in equipment or infrastructure, making tiny steps more affordable than giant leaps. The key is choosing steps that are both sustainable and provide greater returns on investment, accelerating the path toward future growth.
Experience and knowledge within your field or industry are certainly important factors in the decision-making process. That said, relying solely on intuition for matters such as equipment financing might not maximize your results. Data-informed decision making, on the other hand, can provide greater reassurance and persuasive power in moving actions forward.
Data-informed decision making is the process of using data analytics in business decisions. Raw information relevant to your business goals is collected and organized. Trends and highlights in the processed data are evaluated to provide evidence that supports or rejects specific options.
Significant data-informed decision-making benefits include a reduction of bias in the decision-making process and an ability to update data continuously as trends and needs change. Not every decision may have quantifiable data you can analyze, but you can gather the latest information for those that do.
RELATED: How to Make a Business Case for New Equipment
Gathering raw data and getting it into a format where it can best inform your company’s decisions will take some initial work. But once a system is in place, it can prove a valuable ongoing asset to your growth.
The specific data and tools needed will differ from company to company but can be built around the same general framework. Here are four steps to consider in a data-driven process.
Data means little if it can’t be applied to a future vision, goal, or destination. Some questions that can help shape your goals include:
Goals will provide the road map upon which your data, such as key performance indicators, can chart your progress.
Once your goals are established, data collection can begin. Some necessary data might already be regularly collected by your company, but you also might need to establish processes for collecting new information.
A variety of tools and data sets may be available depending on what is important to your process. Both internal and external data sources might be relevant to your needs.
Some metrics to consider, especially around goals relating to equipment financing, include:
It’s important to consider each piece of data separately and as part of a larger picture. For example, a certain part of your service process might be underutilized due to being obsolete or a poor fit for customers’ current needs. It could also be underutilized because other parts of the process can’t keep up with demands or regularly break down.
Where and how each equipment type factors into the process timeline can influence its priority for replacement or upgrading. It’s possible that financing a smaller piece of equipment first could yield greater initial returns than a larger overhaul.
Data can often be overwhelming when considered in its rawest forms. Streamlining and organizing your data can better help make connections, identify opportunities for growth, and provide more persuasive arguments to other decision makers in your company about suggested actions.
Many universal reporting tools can gather multiple data sets and easily display them in a dashboard, along with goals and progress. Such dashboards often can also be customized to display the most pertinent or important data for your needs and remove superfluous figures.
For growth-oriented goals, effective data visualization will better highlight bottlenecks in productivity. Line or bar charts can easily demonstrate which parts of a process are succeeding or struggling from one step to another. It can then be simpler to see which pieces of equipment correspond with problem areas.
Data analytics in business benefits most from multiple sources and perspectives, as each may be capable of highlighting insights that were less visible in others. When analyzing the data you have collected, do not be afraid to bring in outside sources of data for comparison or asking others in your company to provide their interpretations. Both tactics can help you identify new patterns or insights.
Annotating your data can also help make further connections and inferences. This involves labeling your data for easier reference or adding additional context to flesh out the potential importance of certain sections.
Document all the insights arising from your data analysis. This includes new conclusions as well as ideas you might have previously had (and now have the data to confirm). Determine which conclusions are most applicable toward your business goals, sorting them in a manner that makes the most sense to you and key stakeholders.
For a plan including equipment financing, a helpful conclusion report could highlight the projected changes in productivity and returns for replacing or upgraded targeted equipment, as well as a recommended timeline for doing so.
RELATED: How Easy Equipment Financing Helps Grow Your Business
If new or updated equipment is part of your plans to grow, Team Financial Group can provide the financing to help you stay competitive.
We have worked with clients of all sizes to provide customized equipment financing solutions, meeting unique situations and needs. The right financing can help your company meet its future vision – and perhaps help you get there faster than initially expected.
Our financial specialists would love to discuss your equipment financing plans. Just provide some basic information and we’ll get in touch.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
Consumers have come to expect immediate results and instant gratification in today’s tech-driven world, which means business owners need to move products and information faster than ever.
However, small businesses don’t always have resources to dedicate to the latest IT hardware, automation equipment, or staying ahead of technology obsolescence. This is where technology equipment financing comes in. Financing specialists like Team Financial Group can help you make the leap toward cutting-edge technology in a meaningful way while preserving your operating capital.
Making the most of technological advances means properly applying them within your industry sector. The technology should align with your business goals and help drive your business forward.
What does your business need to become more innovative, agile, and resilient? Some options to consider include:
No matter the industry, technologically advanced business equipment can streamline progress. Automating systems can reduce the potential for human error, help recognize problems before they become costly disasters, and build brand loyalty and recognition.
For example, drones are being used everywhere from law enforcement to agriculture, aiding tasks that are often time- and labor-intensive when done manually. Meanwhile, in healthcare, wearable smart tech can help monitor patients, recognize health issues earlier, and provide valuable data for diagnostics.
You can see what today’s tech can do for your business, but progressive solutions may feel financially out of reach. A fleet of drones or wearable tech is a substantial cost outlay for any business, but such investments can help you gain a competitive edge and outpace your competitors.
Make smart decisions about smart devices. Consider how technology equipment financing fits into your current strategy.
RELATED: How Customized Equipment Financing Solutions Benefits Your Business
A trusted financing partner can help ensure your technology financing generates returns greater than your borrowing costs. Getting the right terms on any loans and financing agreements can help you maintain financial security.
At Team Financial Group, we take the time to get to know our clients. We want to know how your business works and see your vision for enhancing your growth. Our 22+ years of industry expertise and 200+ combined years of team experience can help you find the right financing solutions and ensure your current investments elevate your long-term growth prospects.
We often find that technology equipment leasing is the best way to make cutting-edge equipment finance work for our clients. Our FMV lease can help you take advantage of technology that has a short obsolescence cycle, allowing you to quickly and easily upgrade when needed.
RELATED: Top Considerations for Choosing the Right Equipment Financing Partner
If you’re ready for technology equipment financing solutions that will give your company a competitive edge, call Team Financial to see how we can help. Our team of experienced finance professionals can help you enact your vision for long-term, sustainable growth.
Whether the economy is up or down, you can always give us a call for financial advice about managing cash flow or strategically deploying funds. After all, your success is our success.
For more information, don’t hesitate to reach out. Give us a call at 616-735-2393 or fill out our online contact form to see how technology equipment financing could transform your business.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
Outdated equipment can hamper quality, kill productivity, and crush morale. So why do so many employees have to experience the frustration of gear or technology that doesn’t get the job done?
One common reason is that the people who can authorize purchases either don’t know there’s an issue with current equipment or don’t realize how bad or pressing the problem is. So, it might be up to you to help them understand.
If you need to convince a decision maker at your company that the time is right to acquire new equipment, presenting a clear and compelling business case can help.
A business case is a proposal that explains the benefits, costs, and logistics of a potential business decision or purchase. When creating a business case for new equipment, your goal is to convince a decision maker that the requested equipment is worth an immediate investment.
An effective business case should lay out the proposed solution in language that the approver would understand. If you’re part of a small team, you might know the person who will receive your business case — so use that to your advantage. Try to anticipate their concerns and hesitations as well as the benefits that might get them excited about this purchase.
And remember, your business case must include an element of timeliness. You’re not just making the case for why your company should invest in this equipment, but also why it’s important to make the purchase now.
RELATED ARTICLE: The Role of Equipment in Scaling Your Business: 5 Ways an Equipment Purchase Can Help
To write a successful business case for new equipment, you must convince the reader that three things are true:
If you research business cases on the internet, you can find lots of examples and templates. But remember, you’ll want to tailor your business case to your company.
If you’re part of a small business that employs a team of 10 or 15 people and know the company founder, you might not need a long, detailed written proposal. Keeping it short and sweet might prove more effective than sending a busy small business owner a long document they don’t have time to read.
But even if your business case is brief and contains only a handful of points, you still need to cover enough information to make a detailed and convincing case for an equipment purchase. That information should typically include:
RELATED ARTICLE: Get These Tax Benefits With Commercial Equipment Financing
It might not be enough for a decision maker to feel convinced that the company needs new equipment. Cash flow is a critical concern, especially for small and growing businesses, and big equipment purchases are a very common cause of cash flow issues. Many small businesses face a tough choice: let problems with outdated equipment get worse or face a serious cash flow crunch.
Fast and flexible commercial equipment financing can help solve this problem. But many small business owners or managers might not know about their options for equipment financing. Helping them understand the options can provide a big boost to your business case. If you can explain how the company will pay for new equipment without draining the company’s available cash, you’ve made the decision to buy equipment much easier.
Many businesses in Michigan have worked with Team Financial Group and figured out how to upgrade equipment while maintaining financial health. All you need to do is get in touch and we’ll help you figure out the equipment financing option that makes sense for your company.
Two of the financing options that have worked for many of our clients are:
RELATED ARTICLE: Loans, Leases, and Finance Agreements: Which One Is Right for My Business?
At Team Financial Group, we work with clients to find and customize financing solutions that meet their unique needs. Our commercial equipment financing options can improve your business’ cash flow and overall financial health. To get fast, flexible financing today, fill out our simple online application and let us do the rest.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
Growing businesses sometimes face capital challenges that can make investing in new equipment feel difficult. Is it really the right time to focus on equipment and technology, especially if the old equipment seems to be doing its job?
The answer is: yes, it’s always the right time to audit your equipment and figure out where strategic investments could create a healthier, more efficient, and more scalable business. When you continually invest in equipment, your business can spread the costs over time while reaping advantages and avoiding the disruptions that come with equipment failure.
However, the up-front costs of new equipment can overwhelm a business’ cash flow, which is where the right equipment financing partner can come in and help. With fast and flexible financing, your company can start realizing the productivity gains, efficiency improvements, and tax benefits of upgraded equipment at an affordable cost that preserves your working capital.
Here are five ways that new equipment can deliver major advantages when scaling your business.
Upgrading old equipment or purchasing new equipment is one of the most reliable ways to increase productivity and efficiency for a business that aims to scale. The right equipment can make critical business processes more consistent and resilient, increase the quality and quantity of output, and allow your employees to accomplish more with their time.
In some cases, new technologies can automate certain tasks altogether. When low-value repetitive tasks get outsourced to machines, your team can focus their time on activities that make the best use of their skills and provide more value to your business and its customers.
Even when new or upgraded equipment doesn’t significantly change the way your business operates, making consistent investments in your equipment can still be an excellent use of your resources. Many types of high-quality equipment hold their value over time, making your business more asset-rich and resilient. You might be able to leverage an equipment purchase today into much-needed financing for growth later.
Meanwhile, allowing your equipment to become outdated comes with serious risks and downsides. If you adopt an “if it isn’t broke, don’t fix it” mindset, you can end up blindsided by downtime or a total disruption of your operations when a key piece of equipment fails. Getting support and parts for obsolete equipment can eat up time and lead to frustration for your team and customers. New equipment will typically come with warranties, vendor support, and wider availability of replacement parts, all of which translates to more peace of mind and fewer headaches for your business.
RELATED ARTICLE: Business Health: How Equipment Financing Can Help Your Cash Flow
Trends in technology, manufacturing, and engineering are evolving faster than ever. Working with equipment that’s outdated, obsolete, or insufficient for your needs can hamper your ability to keep up with changing customer expectations and put your business behind the curve compared to the competition.
However, the right equipment purchases can deliver improvements in both the quantity and quality of goods or services you’re providing to customers. Your business might even be able to expand your offerings into new products or services altogether, which can lead to new contracts, more loyal and engaged customers, and opportunities in new markets and geographic areas. New revenue streams and customer bases can lead to a more diversified, healthier business.
Of course, the economic uncertainty of the past few years hasn’t made it easy for businesses to invest in equipment. But flexible equipment financing from a trusted partner can help your business make critical equipment purchases and upgrades without massive up-front costs that could jeopardize your working capital. And as the economy stabilizes, businesses who have strengthened and streamlined their operations through calculated investment in equipment will find themselves in the best positions to grow and thrive.
For a growing business and its leadership, tax costs are never far from mind. You might already know that, as a business owner, you can claim the depreciation of certain types of equipment as an expense on your business taxes. But did you know there are other tax benefits specifically designed to help small and medium-sized businesses purchase equipment?
Section 179 is a tax incentive that allows businesses to treat qualifying assets as business expenses and expense the costs of those assets immediately. The potential write-off value under Section 179 is up to $1 million — and you don’t have to own the equipment outright. Financing agreements, loans, and leases can all lead to eligibility for tax benefits under Section 179.
In addition, a deduction based on bonus depreciation can help offset the up-front costs of equipment. This deduction allows you to “speed up” the tax deductions for depreciation of equipment, claiming a large portion of the depreciation value right away. In some cases, business owners can pair bonus depreciation with Section 179 to deduct the full cost of eligible equipment purchases from their business taxes for the year. Note that you must take the deduction for bonus depreciation in the first year that the relevant equipment goes into service, and there are various requirements and restrictions.
To learn more about the details of Section 179 and bonus depreciation for equipment purchases, read our previous blog article on the topic.
RELATED ARTICLE: Get These Tax Benefits With Commercial Equipment Financing
Labor is one of the toughest constraints that growing businesses face today. Companies across so many industries are struggling to fill out their teams and find workers who have the right skillsets. In this hyper-competitive labor market, it’s critical for businesses to offer their teams a great working environment that lets employees do their best work. And having good-quality, up-to-date equipment is an essential part of building that environment.
Equipment purchases and upgrades don’t just deliver bottom-line improvements that can be measured in dollars and cents — they also boost employee morale. Our financing specialists have repeatedly seen firsthand how an equipment purchase or upgrade can create excitement within a company and make employees feel more invested in their roles.
On the other hand, employees who have adjusted to working on cutting-edge equipment may not even consider your company if they think your equipment is out of date. Would you take a role at a company where the equipment might slow you down, cause you frequent frustration, or even injure you? If your business continually invests in equipment, your prospective and current employees won’t have to face this choice, and your teams will be much happier for it.
RELATED CLIENT SUCCESS STORY: Achieving Rapid Growth at Scale: Integrated Technology LLC (ITg)
Holding onto old and outdated equipment can represent a risk for your business in various ways. In a manufacturing context, older equipment — even when well-maintained — might not incorporate recent safety advances and could increase the risk of a workplace injury. And older IT and technology equipment can expose your business to security breaches, cybercrime, ransomware, and a host of other digital threats.
As your business grows, so will the potential sources of risk and liability. A security breach or serious workplace injury can harm your business’ reputation, profitability, and employee morale. It’s possible that a single lawsuit over outdated, hazardous equipment could end up costing you far more than you would have spent updating that equipment in the first place.
When you make sure your employees have the right equipment to do their job safely and efficiently, you set an example and let your employees know that their health, security, and workplace experience all matter to you. Plus, in addition to digital security advances, the latest equipment may include anti-theft and security features that make your company less vulnerable to burglary and other physical forms of crime.
At Team Financial Group, we take a personal approach to every financing request. Our equipment financing specialists can help you get organized and gather information to secure the financing you need. You can use our easy online application to start the financing process now and let us guide you from there.
If you have questions that you’d like to ask before you get started with an application, fill out our online contact form or give us a call at 616-735-2393. We’re here to help.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
You’ve decided your business needs equipment financing, and you want to apply. But what will that process look like, and what information and documentation will you need?
Here, we’ll explain the business loan application process and describe all the supporting information you’ll need to secure equipment financing for your business.
As you read this article, keep in mind that this guide is intended for those who want to come into the application process as prepared as possible. If at any point the process sounds confusing or overwhelming, or if you decide you just want to get the application moving and figure the rest out later, we can help!
When you work with Team Financial Group, you can get started with only a basic application consisting of your contact information and business name. We’ll use that information to get in touch with you. Then, we can provide personalized help and guidance through the entire application process.
Read on to learn about the steps you can expect during the equipment financing process.
The first step in the process involves finding a lender or financing partner. Some business owners will go right to a bank during this step, not realizing they could work with a more specialized equipment financing partner who can offer significant advantages over a bank.
What if you could work with a lender who not only understands your business inside and out but also can offer more flexibility, personalization, and attention than a bank?
A specialized commercial equipment financing partner like Team Financial Group can guide you through the application and funding process, but that’s just the beginning for us. We build relationships with our clients and become their trusted partner, which is why many of our clients come back to us when they need additional financing — or even when they’re just looking for help and advice.
However, banks can still play an important role in financing a business. In fact, many of our clients come to us via referral from banks. Banks are especially useful for securing larger lines of capital for general use, like a business line of credit.
When evaluating potential lenders, consider all your available options and don’t overlook specialized equipment financing companies. With the right financing partner on your side, the entire financing process can become much easier.
RELATED ARTICLE: How to Choose the Right Commercial Lender for Your Business
You might be surprised how simple the initial application for financing can be. Often, you can get the process started with a few basic details about your business and the financing you’re looking to secure.
Your application will typically need to include:
Your lender will use your legal business name to verify that the business is registered at the state or local level. In addition to your business’ name, your lender will probably require you to specify the legal structure of your business (such as an LLC, corporation, or sole proprietorship). You’ll also need to provide your state and federal employer identification number (EIN).
Your lender will want to communicate with you throughout the application process, so you’ll need to provide the business address and mailing address for your company. You should also give them phone numbers and email addresses for key contacts such as owners, stakeholders, and high-level management.
Your lender needs to understand what you’re trying to accomplish with your financing and which equipment or technology you plan to purchase. If you’ve already found a vendor and have a quote for your equipment, you should provide that document to your lender.
If you haven’t found a vendor yet or haven’t settled on the exact equipment you want to purchase, that’s okay. Instead of a quote, you can provide a description of the equipment you intend to buy. Try to describe the equipment in as much detail as you can, including:
Your lender will typically need to check the personal credit of the business’ owners. To access credit histories and scores, your lender will need the following information for each owner of the business:
RELATED ARTICLE: 7 Tips for Purchasing New Equipment for Your Business
Each lender’s application form is different. If you decide to work with Team Financial Group, we make the application process as easy as possible for you. You can get started with a simple online application you can fill out in under a minute. All you need to give us is your contact information and business name.
Once you’ve filled out the basic application form, you’ll receive an email with the option to download the full application. If you’ve gathered the information listed so far in this article, you can begin filling out the full application while our financing specialists get in touch with you.
However, if you don’t have all your information gathered yet or aren’t sure exactly what equipment or financing option you want, don’t worry. You can still start the application process now and we’ll guide you from there.
For smaller financing amounts, your personal credit history could be all that your financing partner needs. But for larger or more complex financing applications, your financing partner might ask for additional information such as:
So, what amount defines a “smaller” or “larger” financing request? It depends on your financing partner. Team Financial Group can often deliver financing amounts between $5,000 and $75,000 based on a personal credit history. We tend to require additional financial documentation when the loan request or total exposure with a business reaches $100,000.
However, keep in mind that these amounts are generalizations, not rules set in stone. The requirement for more detailed financial statements can vary depending on the size, complexity, and nature of your business.
RELATED ARTICLE: How to Choose the Right Commercial Lender for Your Business
At Team Financial Group, we take a personal approach to every financing request. Our equipment financing specialists can help you get organized and gather the information to secure the financing you need. You can use our easy online application to start the financing process now and let us guide you from there.
If you have questions that you’d like to ask before you get started with an application, fill out our online contact form or give us a call at 616-735-2393. We’re here to help.
The content provided here is for informational purposes only. For financial advice, please contact our commercial financing experts.
RCC Business IT has provided comprehensive IT and cybersecurity support to Michigan businesses for nearly 30 years. The technology expertise at RCC Business IT runs deep, and the company’s team of specialists can tackle any IT project or custom software request to achieve on-time, on-budget delivery.
But even the best expertise can only take an IT project as far as its funding allows. And that’s where Team Financial Group comes in.
For more than 10 years, RCC Business IT has partnered with Team Financial Group to provide attractive, cost-effective IT equipment leasing options for customers.
RCC Business IT President Steve Eaton says that his team can count on Team Financial Group to answer requests efficiently and keep the quote process moving on IT infrastructure projects. Steve also says that his customers appreciate Team Financial Group’s flexibility in the approval process and ability to offer a variety of tools that make lease options more efficient.
But more than anything else, says Steve, customer support is what makes Team Financial Group different than other lenders.
“The feedback we’ve received about Team Financial Group has always been excellent,” Steve says. “That’s the No. 1 reason we feel confident referring all our leasing-candidate customers to Team Financial Group.”
To get in touch with Steve and the team at RCC Business IT, visit their website. If you need a financing partner for IT equipment or any other commercial equipment, contact Team Financial Group today.
“For any company looking for a finance partner,” Steve says, “it’s worth your time to interview Team Financial Group.”