Equipment financing is often a long-term commitment, but that doesn’t mean the original financing structure will always be the best fit for your business.
Interest rates change, cash flow shifts, and new opportunities can arise as your business develops. Sometimes a financing agreement that made plenty of sense two or three years ago just no longer fits the way your business operates today.
That’s where equipment refinancing can come in. But it isn’t automatically the right move.
At Team Financial Group, we believe financing decisions should be based on what helps your business move forward. Here’s what to consider when deciding whether refinancing your equipment is worth it.
Equipment refinancing generally involves taking out new financing to pay off an existing equipment loan or other obligation.
For example, suppose your business financed a piece of manufacturing equipment several years ago. You still owe money on that financing, but your financial needs have changed. You might refinance the remaining balance into a new agreement with a different term or payment structure.
Depending on the situation, refinancing may help you:
The important question is whether equipment refinancing meaningfully improves your overall financial position.
There are several situations where refinancing can be a valuable financial tool.
Cash flow needs can change significantly over the life of a loan.
Maybe your business took on financing during a strong growth period, but your industry is now experiencing a seasonal slowdown. Or perhaps you’re investing more heavily in hiring, inventory, marketing, or expansion and want additional breathing room.
Refinancing may allow you to restructure the remaining balance over a different term and potentially reduce your monthly payment. That doesn’t necessarily reduce the total amount you’ll pay over time, but improved monthly cash flow can be valuable if it helps your company maintain flexibility and continue investing in growth.
RELATED: How Construction Equipment Financing Can Improve Seasonal Cash Flow Management
If you originally financed equipment when your company was newer, had less revenue, or had a thinner credit profile, your original financing terms may reflect those circumstances.
Several years later, you may have stronger business credit, greater revenue, and a stronger repayment history, among other strengths. They may make it worthwhile to explore whether a new financing structure is available that better reflects your current financial position.
Sometimes the issue is an agreement that has become inconvenient as your business changes. For example, you may want:
Refinancing can provide an opportunity to reassess how the debt fits into your broader financial strategy.
Working capital is what keeps your business moving from day to day. If too much cash is going toward equipment debt, refinancing may help free up money for priorities including payroll, material marketing, hiring, and expansion.
The goal here isn’t necessarily to eliminate your debt entirely. However, your debt structure shouldn’t prevent you from pursuing profitable opportunities if you can help it.
In some situations, businesses own equipment that has significant value compared with what they still owe. That equity may create additional financing possibilities.
Depending on the structure and lender, businesses may be able to use equipment value as part of a refinancing strategy to improve liquidity or support other business investments. This can be especially useful for equipment-intensive companies that have valuable assets but would prefer not to tie up all of their financial resources in those assets.
Refinancing can be useful, but it isn’t free and it doesn’t automatically create savings.
Before making a decision, consider the potential downsides:
If you only have a few payments remaining, refinancing may create more complexity than value. Starting a new financing agreement could extend your obligation well beyond the original payoff date and potentially increase your total financing costs.
In this type of situation, it may be better to finish paying off the existing agreement and reassess your financing needs afterward.
Lower monthly payments can be attractive, but always consider the bigger picture.
Suppose you have three years remaining on your current equipment financing and refinance the balance into a five-year term. Your monthly payment may decrease, but you could end up paying financing costs for two additional years.
That doesn’t automatically make refinancing a bad decision. Improving your cash flow could be worth the additional time and cost. But any sort of tradeoff like this should be thought through and intentional.
Ask yourself what your business will gain from the lower monthly payment and whether that benefit outweighs the added long-term cost.
RELATED: What Happens When an Equipment Finance Lease Expires?
Before refinancing, review your existing financing agreement for:
Then compare those costs with the potential benefit of the new financing. A lower payment isn’t necessarily a better deal if the cost of getting there is too high.
Refinancing an aging piece of equipment deserves special consideration.
If a machine is likely to require replacement soon, extending debt on that asset could leave you making payments on equipment that is no longer productive or reliable. In that situation, of course, replacing the equipment might be the stronger long-term decision.
Think beyond whether the equipment still operates today. Consider repair costs, downtime, productivity, resale value, and how long you realistically expect to keep using it.
RELATED: The Hidden Costs of Delaying Critical Equipment Upgrades
Sometimes the best move is no move at all.
If your existing financing has reasonable payments, favorable terms, and a manageable remaining balance, refinancing simply for the sake of refinancing may not provide much value.
If refinancing isn’t the right fit, you may still have other ways to improve your financial flexibility.
If your concern is preserving working capital for an upcoming purchase, you may not need to refinance existing equipment. Financing the next purchase instead of paying cash could provide the flexibility you need without changing your current obligations.
If your company owns equipment outright, a sale-leaseback may be another way to access capital.
With a sale-leaseback, the business sells equipment to a financing company and then leases it back, allowing operations to continue while freeing up cash that was previously tied up in the asset.
Sometimes the best solution is replacing an inefficient asset rather than refinancing it. Newer equipment may reduce your repair costs, downtime, labor, and energy consumption, which can all add up in certain situations.
If an aging asset is becoming expensive to maintain, financing an upgrade could provide a stronger return than extending financing on older equipment.
Individual financing decisions shouldn’t happen in isolation.
If your business has multiple equipment purchases coming up, seasonal revenue changes, or expansion plans, it may be more useful to develop a broader financing strategy instead of simply refinancing one existing obligation.
When evaluating refinancing, consider:
For some businesses, paying slightly more over the long term in exchange for greater financial flexibility may make sense. For others, paying off the existing financing as quickly as possible may be the better strategy.
The right answer for you depends on what your business needs next.
RELATED: How to Create an Equipment Budget Built for Long-term Growth
Any consideration of refinancing should begin with a conversation about what you’re trying to accomplish.
At Team Financial Group, we take the time to understand your business, your existing obligations, your equipment, and your goals. If refinancing makes sense, we can explore financing structures designed to support your cash flow and long-term plans.
And if refinancing isn’t the best option, we can discuss other possibilities including financing new equipment, structuring future purchases differently, or considering other equipment financing solutions.
As an independent equipment financing company, Team Financial Group can often take a more flexible, personalized approach than traditional lending institutions. Instead of relying solely on a rigid formula, we work to understand the broader financial picture and find solutions that make sense for the individual business.
The best equipment financing strategy isn’t necessarily the one with the lowest monthly payment or the shortest term. It’s the one that supports your business goals while maintaining the financial flexibility you need to operate and grow.
Equipment refinancing can be a powerful tool when it improves cash flow, better aligns payments with your business, or replaces financing that no longer makes sense. But there are also times when keeping your existing financing, replacing aging equipment, or choosing another strategy is the smarter decision.
If you’re considering refinancing equipment and aren’t sure which direction to take, talk with Team Financial Group. We can help you evaluate the options and build a financing strategy around where your business is today and where you want it to go next.
Your business needs new equipment. You’ve found the right machine, vehicle, or technology, negotiated the purchase price, and determined that the investment makes sense.
Now comes another important decision: How should you pay for it?
For many business owners, the choice comes down to three options: leasing the equipment, financing it with an equipment loan, or paying cash. Each approach has advantages and disadvantages, and there isn’t one answer that works for every business or every purchase.
Here’s what business owners should consider when comparing a lease vs. loan vs. cash purchase.
RELATED: Learn More About Our Equipment Financing Options
Paying cash is certainly the simplest approach. Your business pays the purchase price, takes ownership of the equipment, and doesn’t have an ongoing financing obligation.
The most obvious advantage is that you don’t have to pay interest or other financing costs. If a machine costs $100,000, for example, paying cash means you aren’t adding borrowing costs to that purchase.
You also own the equipment immediately without a lender or lessor having a financial interest in it.
Paying cash can make sense when:
The biggest disadvantage is what happens to your working capital.
Spending cash on equipment means your business has that asset, but it also has that amount less in cash available for payroll, inventory, marketing, repairs, expansion, or unexpected opportunities. That creates an opportunity cost.
For example, imagine you spend $150,000 in cash on a piece of equipment. Two months later, you win a major contract that requires hiring employees and purchasing additional materials. If most of your available capital is tied up in equipment, you may have fewer options for taking advantage of that opportunity.
Cash provides flexibility. Once you convert it into equipment, that flexibility decreases. That’s why even businesses that can afford to pay cash sometimes choose financing instead.
An equipment loan allows you to acquire the equipment now while paying for it over a predetermined period, typically with principal and interest. The equipment itself will often serve as collateral for the financing.
For businesses that expect to keep equipment for many years, a loan can provide a useful balance between ownership and cash-flow management.
The primary benefit is preserving working capital.
Rather than taking the full cost out of the business at once, you can spread that investment across several years. That leaves more money available for the other expenses and opportunities that keep your company growing.
Loans can also offer predictable payments, particularly when they have fixed rates. Knowing what you’ll owe each month makes budgeting and forecasting easier.
Equipment loans may be a good fit when:
Financing generally means paying interest or financing costs, so the total amount paid can be higher than the cash purchase price.
You’re also taking on a recurring financial obligation. Before financing equipment, you should make sure the payments comfortably fit within your expected cash flow.
Loan terms matter, too. Business owners should understand any fees, collateral requirements, early payoff provisions, and other conditions before signing. A good financing partner should make these terms clear and help you find a structure that fits your business.
Leasing can be another effective way to acquire business equipment without paying the full purchase price upfront. But not all leases work the same way.
For example, a Fair Market Value (FMV) lease generally allows you to use equipment for a specified period and then return it, continue leasing it, or potentially purchase it for its fair market value at the end of the term.
A $1 buyout lease is structured differently. It generally gives the business a path toward ownership, with the equipment purchased for a nominal amount at the end of the lease.
Understanding the lease structure and your end-of-term options is critical before deciding how you wish to proceed.
Leasing can be particularly attractive for equipment that becomes obsolete quickly.
Technology is a good example. If you know you’ll probably want newer equipment in three or four years, a structure that makes replacing the equipment easier may be preferable to owning an aging asset.
Leasing may make sense when:
Leasing can also help businesses develop more predictable equipment refresh cycles rather than waiting until old equipment fails before replacing it.
Depending on the lease, you may not automatically own the equipment when the term ends. There can also be return conditions, buyout requirements, or other end-of-term obligations. That makes it important to understand exactly what happens at the end of the agreement.
Instead of asking which option is universally “best,” ask which option best supports your business. Start with these questions.
Having enough money in the bank to purchase equipment doesn’t necessarily mean paying cash is the best use of that money.
Consider how much working capital you need to comfortably operate your business and respond to unexpected situations. Then consider what else that cash could accomplish.
If you’re buying a durable piece of machinery that you expect to operate for many years, ownership through cash or a loan may be attractive. But if the equipment needs frequent upgrades, leasing may provide you with greater flexibility.
Consider the return you expect from your investment.
If a $200,000 machine will immediately increase production and generate additional revenue, financing may allow the equipment’s increased output to help support its payments.
RELATED: Cap Ex Spending and Planning Ahead
Large cash purchases can create significant fluctuations in your budget. Financing or leasing can convert those large expenditures into more predictable payments.
That can make forecasting easier and leave additional cash available for other needs.
RELATED: How Construction Equipment Financing Can Improve Seasonal Cash Flow Management
Your next opportunity matters just as much as today’s equipment purchase.
If you’re expanding rapidly, preserving capital may give you more room to hire, purchase inventory, open another location, or take on larger projects.
RELATED: Unlocking Growth with Data-informed Financing
Taxes can also affect the lease vs. loan vs. cash decision.
Depending on the equipment, financing structure, and current tax rules, your purchase may qualify for deductions such as Section 179 or depreciation benefits.
Importantly, paying cash isn’t necessarily required to qualify for certain equipment-related tax deductions. Eligible financed equipment may also qualify when applicable requirements are met.
Tax treatment can vary significantly depending on the transaction and your business’s circumstances, however. Your accountant or tax professional can help you understand how different purchasing and financing options could affect your specific situation.
You don’t have to decide between leasing and financing on your own.
At Team Financial Group, we work with business owners to understand what they’re buying, how they plan to use it, and what they’re trying to accomplish financially.
Instead of forcing every business into the same financing structure, we can explore options based on the factors and needs specific to each business. That could mean an equipment loan, a $1 buyout lease, a Fair Market Value lease, or another financing structure appropriate for your circumstances.
And because we’re an independent equipment financing company rather than a traditional bank, we can take more flexible, personalized approaches to finding solutions.
If you’re planning an equipment purchase and aren’t sure which financing option makes the most sense, talk with us at Team Financial Group. The right equipment can help your business grow, and the right way of paying for it can help make sure you have the financial flexibility to keep growing after the purchase is complete.
While nearly every business recognizes the value of keeping technology current, many postpone upgrades because of the cost. Large technology purchases can place pressure on cash flow, making it tempting to stretch the life of aging equipment for another year (or several).
Unfortunately, delaying technology investments often creates problems of its own. Older equipment becomes slower, more expensive to maintain, less secure, and increasingly incompatible with newer software. Productivity suffers, downtime becomes more common, and employees spend more time working around outdated systems than doing the work they need to do.
Businesses can feel caught between the rock of necessity and the hard place of executability. But the good news is that technology upgrades don’t have to disrupt your operations or your budget. With a thoughtful financing strategy, your business can stay current while maintaining healthy cash flow and minimizing operational interruptions.
At Team Financial Group, we help businesses develop financing solutions that make technology upgrades predictable, manageable, and aligned with long-term business goals.
Unlike heavy machinery or commercial vehicles that may remain productive for decades, technology evolves quickly.
Computer hardware, networking equipment, software platforms, medical devices, and manufacturing automation all have relatively short innovation cycles. Today’s cutting-edge equipment may become outdated within just a few years. Waiting until equipment completely fails often means your business has already been operating at a disadvantage.
Older technology can create challenges such as:
Instead of viewing technology as a one-time purchase, successful businesses increasingly think of it as an ongoing investment that requires regular planning and periodic refreshes.
Many businesses focus primarily on the purchase price of new technology. However, the hidden costs of waiting are often much greater than expected.
Older equipment is more likely to fail unexpectedly. And those outages often don’t just interrupt one employee. They may halt entire departments, delay customer orders, or postpone critical projects.
Planned upgrades are almost always less disruptive than emergency replacements.
Repair expenses often increase as technology changes. Replacement parts become more difficult to find. Manufacturers discontinue support. Service contracts become more expensive.
Eventually, businesses might spend more maintaining old systems than they would financing new ones.
Cybersecurity is no longer just an IT issue. It’s one the whole business must be aware of.
Older hardware and unsupported software often stop receiving security updates, making them more vulnerable to cyberattacks, ransomware, and data breaches. Technology investments can help strengthen your organization’s security while reducing operational risk.
Sometimes the greatest cost for your business isn’t what you’re spending, but what you’re unable to do. Outdated technology may prevent your business from:
Modern technology often creates opportunities that older systems simply cannot support.
RELATED: The Hidden Costs of Delaying Critical Equipment Upgrades
Rather than waiting until systems fail, many organizations create formal technology refresh plans. Such plans help businesses budget for upgrades before equipment becomes a liability.
When considering your business’s strategy, you should:
Different types of technology have different useful lives. For example:
Specialized production equipment varies depending on usage and manufacturer recommendations.
All these timeframes largely depend on who you ask, the type of equipment you use, and how often you use it. But understanding these general timelines helps avoid surprise expenses.
RELATED: Building a Future-Proof Business with Smart Investments
At least once each year, evaluate your technology inventory. Ask questions such as:
These reviews help identify upgrade opportunities before they become emergency necessities.
Not every upgrade needs to happen immediately. With enough leeway and foresight, you can prioritize your upgrades over time.
Identify which systems have the greatest impact on daily operations. You might want to start with technology that directly affects production, customer service, data security, employee productivity, and sales.
This approach allows you to maximize the return on every technology investment.
Financing changes the conversation from “Can we afford this?” to “How can we make this fit our long-term strategy?”
Instead of making one large capital expenditure, financing spreads costs into predictable monthly payments. That provides several important advantages.
Technology isn’t the only investment your business needs to make. By financing equipment, you can preserve cash for payroll, inventory, expansion, and unexpected opportunities.
Healthy cash flow provides flexibility throughout the year.
One of the biggest advantages of financing is predictability. Rather than absorbing large, irregular technology purchases, businesses can budget consistent monthly payments.
Predictable payments make it easier to:
Instead of experiencing significant spikes in capital spending every few years, technology becomes a manageable operating expense.
New technology often begins generating value immediately as it improves efficiency and productivity.
Financing allows the cost of the equipment to be spread across the period in which your business is benefiting from its use. This creates a better alignment between investment and return.
RELATED: Creating a Tech-Driven Business Model with Smart Technology Equipment Financing
Perhaps the greatest benefit of financing technology is the ability to stay current. Rather than holding onto aging equipment long after it should be replaced, businesses can establish planned refresh cycles.
Refresh cycles allow organizations to:
Instead of reacting to technology problems, you’re proactively planning for continuous improvement.
Many businesses find that a scheduled refresh strategy actually lowers total technology costs over time because it reduces emergency repairs, unexpected downtime, and productivity losses.
Technology investments look different depending on your industry.
Construction companies may finance GPS systems, estimating software, or drones.
Manufacturers may upgrade automation equipment, robotics, or CNC controls.
Medical practices may invest in diagnostic equipment or imaging technology.
Transportation companies often replace fleet management systems and dispatch software.
Professional service firms may modernize workstations, servers, cloud infrastructure, or cybersecurity systems.
Regardless of your industry, the goal remains the same: keeping technology aligned with your business objectives while maintaining healthy cash flow.
At Team Financial Group, we understand that technology investments are about much more than purchasing new equipment. They’re about helping businesses become more productive, competitive, and prepared for the future.
That’s why we work closely with business owners to build financing strategies that support long-term growth. Our approach includes:
Every business has different technology needs. We help structure financing around your goals, budget, and operational requirements.
Technology opportunities often move quickly. Our streamlined approval process helps businesses move forward without unnecessary delays.
Rather than forcing every customer into the same financing model, we work to create payment schedules that align with your business’s financial situation.
Technology will continue to evolve, and your financing strategy should evolve with it. We aim to build lasting relationships with our clients, helping them plan not only today’s purchase but tomorrow’s upgrades as well.
Technology should help your business operate more efficiently, not hold it back.
Waiting until equipment becomes unreliable often results in higher repair costs, lower productivity, frustrated employees, and missed opportunities. By creating a technology refresh strategy and financing upgrades with predictable monthly payments, your business can stay current without disrupting day-to-day operations or straining cash flow.
At Team Financial Group, we’re committed to helping businesses invest in the technology they need through flexible financing solutions that support growth. Whether you’re planning a company-wide technology refresh or replacing a single critical system, our team is ready to help you develop a financing strategy that works for today and positions your business for tomorrow.
Contact us today and let’s schedule a time to discuss your technology equipment financing plans.
Equipment financing can be a highly beneficial business investment. Whether it’s heavy equipment or critical technology, financing allows you to acquire the tools you need while preserving working capital.
But while financing itself can be beneficial, the details of the financing agreement matter. Hidden fees, restrictive terms, and unfavorable conditions can turn what appears to be a good deal into an expensive mistake.
As a business owner, you don’t need to become a financing expert overnight. However, understanding a few common warning signs can help you avoid surprises and choose a financing partner that truly supports your success.
When evaluating financing options, many business owners focus primarily on the monthly payment. While affordability is important, the monthly payment only tells part of the story.
The structure of the contract affects:
Taking time to review the details before signing can save your business significant money and frustration later.
RELATED: 7 Equipment Financing Myths Debunked
One of the most common issues in equipment financing contracts is the presence of fees that are not clearly explained upfront.
These may include:
A financing agreement should clearly disclose all costs associated with the transaction. If fees seem vague or difficult to understand, ask questions before signing.
For example, a contract might advertise an attractive monthly payment but include substantial fees that increase the total financing cost. Without reviewing the complete agreement, those expenses may go unnoticed until later.
Many business owners focus on acquiring equipment and overlook what happens when the financing term ends. Those details can be especially important with leases.
Before signing, make sure you understand:
For example, a Fair Market Value (FMV) lease may require you to purchase the equipment at its market value at the end of the lease if you want ownership. A $1 Buyout Lease, on the other hand, typically allows ownership for a nominal amount.
You could find yourself facing unexpected costs later if these details aren’t clearly explained in the terms.
RELATED: What Happens When an Equipment Finance Lease Expires?
Businesses rarely experience perfectly consistent revenue throughout the year. Construction companies often have seasonal cycles. Agricultural businesses have harvest periods. Transportation companies may see fluctuations based on customer demand.
Unfortunately, some financing agreements offer little flexibility when cash flow changes. Warning signs of payment rigidity include:
A financing solution should fit your business and not force you to fit the financing. The right lender understands your industry and works to structure payments in a way that aligns with your revenue cycle.
RELATED: How Construction Equipment Financing Can Improve Seasonal Cash Flow Management
Many lenders require some form of personal guarantee, particularly for small businesses. However, not all guarantees are structured equally.
Pay close attention to:
Some agreements contain provisions that extend beyond the equipment being financed and create additional obligations that may not be obvious at first glance. If any language seems confusing or overly broad, ask for clarification. A trustworthy financing partner should be willing to explain exactly what you’re agreeing to.
Perhaps the biggest red flag isn’t in the contract itself, but how the lender is presenting your financing options to you.
Be cautious if a lender:
Financing should be a partnership, not a high-pressure sales transaction. A good financing provider wants you to understand your options and feel confident in your decision.
If you feel rushed or uncertain, take a step back and ask additional questions before moving forward.
Before committing to financing, consider asking:
The answers to these questions can reveal a great deal about whether a financing program is designed with your best interests in mind.
At Team Financial Group, we believe equipment financing should help businesses grow without creating unnecessary obstacles. That’s why we focus on transparency, flexibility, and personalized service.
When you work with Team Financial Group, you can expect:
We take the time to explain financing options and answer questions. Our goal is to ensure you understand the terms and feel comfortable with your decision.
We also put in real effort to understand your industry and the timings and challenges that surround it.
Every business is different. We work to create financing structures that align with your cash flow, equipment needs, seasonal revenue flow, and long-term goals.
We offer a variety of financing solutions, including:
We view financing as the beginning of a relationship that extends beyond the transaction. Our team works alongside clients to support their growth over the long term. We love success stories and want to see your business thrive.
Equipment financing should provide your business with opportunities, not surprises.
By watching for hidden fees, understanding end-of-term obligations, evaluating payment flexibility, reviewing liability provisions, and choosing a transparent lender, you can avoid many of the common pitfalls found in equipment financing contracts.
Most importantly, don’t be afraid to ask questions. A reputable financing partner should welcome them.
At Team Financial Group, we’re committed to helping businesses secure the equipment they need through straightforward, flexible financing solutions designed around their goals.
If you’re evaluating equipment financing options and want to discuss your situation with an experienced team, contact Team Financial Group today. We’ll help you understand your options and find a financing solution that works for your business.
Walk into almost any store and odds are you’ll see something Impact Label has produced. From small, local companies to Fortune 500 brands, the custom label solutions manufacturer ships its work to customers around the world.
Specializing in vinyl, polyester, and polycarbonate overlays, the company’s products are built to last the life of whatever they’re attached to, from kayaks and engines to boats and medical device equipment.
Based in Galesburg, Michigan, Impact Label’s leadership took a hard look at where the company was in 2020—and where it wanted to go. Antiquated equipment was making the company less effective and competitive, and feedback from sales reps and customers reinforced that something had to change.
“We took a hard look at the business and said, ‘Hey, if we want this to last for the long term, what do we need to do?’” Impact Label Vice President and General Manager Matt Berry said. “That started with an investment in equipment.”
Impact Label needed to invest in more modern equipment to remain a leader in its industry. And to do that, the company needed a financing partner that could provide fast and flexible financing options.
Team Financial Group financed a polyurethane doming machine as part of Impact Label’s first major equipment project in 2020. Doming adds a 3D-effect resin layer over a label, both as a visual embellishment and a way to extend its life. Because the polyurethane is rated for outdoor, marine, and automotive use, the process fits squarely with Impact Label’s goal of consistent durability.
What made the project possible was Team Financial Group’s willingness to look beyond just financial statements and see Impact Label’s vision for long-term growth and sustainability.
“They took a chance with us on our first piece of equipment. We had a really strong balance sheet, but the profitability wasn’t where we wanted it to be,” Berry said. “They allowed us to get this piece and, ever since, they’ve been open to investing in Impact and helping us acquire new equipment.”
RELATED ARTICLE: How to Make a Business Case for New Equipment (and Why Equipment Financing Can Help)
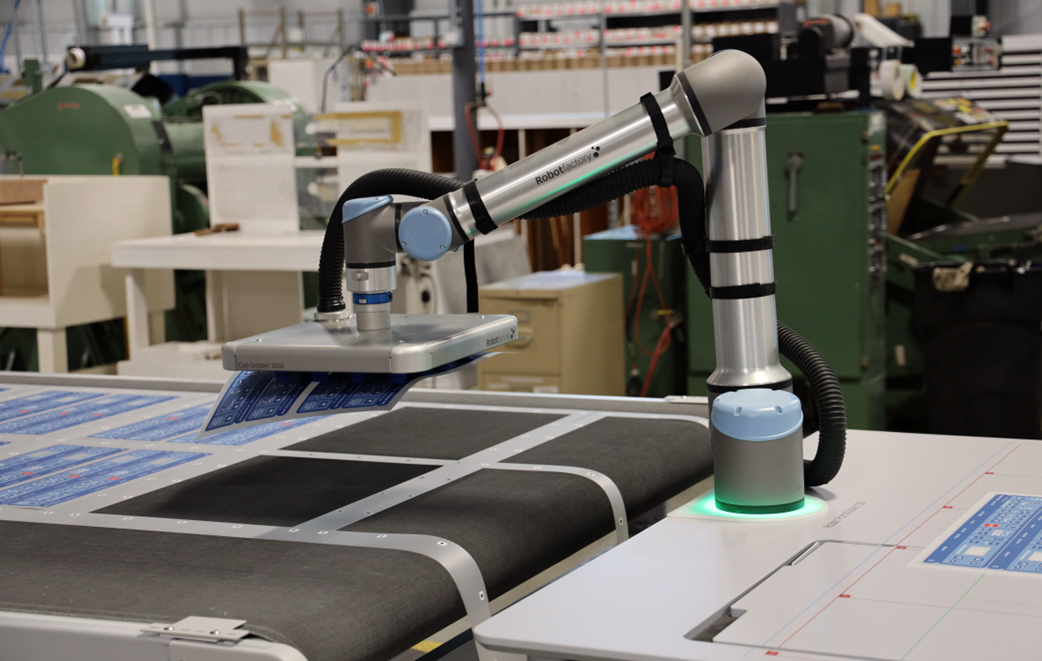
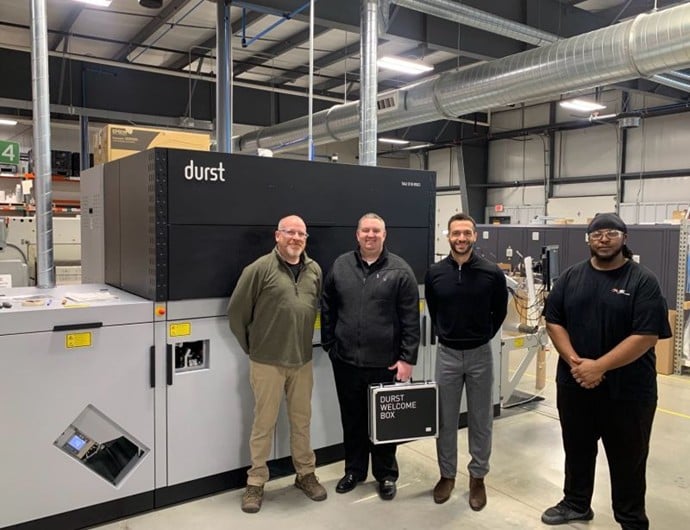
Since 2020, Team Financial Group has helped finance additional equipment investments at Impact Label, culminating in the company’s largest purchase to date: a Durst Tau press installed at the end of 2025. The cumulative effect has been transformational, according to Berry.
“It’s really put us at the forefront of our industry,” Berry said. “We’re definitely in the top 1% with our equipment capabilities. There’s no other company that has the variety and advanced equipment that we have.”
For Impact Label, Team Financial Group stood out from the steady stream of equipment-finance cold calls by doing what the competition didn’t: show up.
“They visited our facility, and they’ve followed up regularly to see if there’s anything they can do to help us,” Berry said. “It feels like somebody who’s there if you have an issue. You can call them up and work through it together instead of just being a piece of paper that somebody signs off on.”
That hands-on approach has continued throughout the relationship. After Impact Label installs each new piece of equipment, the Team Financial Group team travels to the facility to see everything in person and check in on how things are going.
The financing process itself also has been smooth.
“They make everything very easy,” Berry said. “As soon as you need the money, it’s there. When they say they’re going to have it, they’ll have it for you.”
If you’re looking for a financing partner that can help your organization make equipment upgrades to stay competitive, contact Team Financial Group today.
We offer many different financing options, often with same-day approval. To get started, give us a call at 616-735-2393 or fill out our short online contact form.
Upgrading equipment is a decision that many business owners push down the priority list, and we understand why it happens. If a machine is still running, a vehicle is still drivable, or a system is still “good enough,” it can feel easier to delay the investment and focus on more immediate needs.
But holding onto outdated equipment often comes with hidden costs that can quietly impact your productivity, profitability, and long-term growth.
At Team Financial Group, we work with businesses every day that weigh the pros and cons of equipment upgrades. In many cases, waiting too long ends up being more expensive than making a strategic upgrade at the right time.
Let’s discuss how to evaluate your equipment, the real costs of delaying upgrades, and how financing can help you move forward without putting pressure on your cash flow.
The key to avoiding costly delays is having a clear, proactive plan. Instead of waiting for equipment to fail, successful businesses regularly evaluate their assets and make strategic upgrade decisions.
Here’s how to get started:
Start by creating a detailed list of your equipment, including:
This gives you a clear picture of where you stand and which assets may need attention.
If you’re spending increasing amounts on repairs, that’s often a sign it’s time to upgrade.
You can also measure proportionally. If annual repair costs are approaching a significant percentage of the equipment’s value, replacement may be the more cost-effective option.
Either way, keep a comprehensive history of your repair costs. Tracking them over time will help you identify trends before they become major problems.
RELATED: How to Make a Business Case for New Equipment
Ask yourself:
Even if equipment is still functioning, outdated technology can limit your output and reduce your competitiveness.
Older equipment may not meet current safety standards or regulatory requirements. This might increase liability risks and potentially lead to fines or operational disruptions.
Upgrading can help protect your team, your business, and your reputation.
Your upgrade plan should support where your business is going, and not just where it might stand today.
If you’re planning to:
Then your equipment strategy should reflect those goals.
RELATED: Building a Future-Proof Business with Smart Investments
It’s easy to focus on the upfront cost of new equipment. But the real financial impact often comes from waiting too long to replace outdated assets. Then you have the cost of new equipment on top of compounding additional losses.
Here are some of the most common and costly consequences:
Older equipment often operates slower, less efficiently, and with more interruptions. This leads to longer project timelines, reduced output, and increased labor costs.
Even small inefficiencies can compound over time, especially in high-volume operations.
As equipment ages, repairs become more frequent and expensive. The longer equipment runs without upgrades the more likely you are to:
At a certain point, you’re reacting to problems as much if not more than doing the work.
The costs of unexpected equipment breakdowns aren’t just measured in money, but time as well.
We already mentioned downtime as a consequence. But the effects of that downtime can branch out across your business and lead to:
In many industries, even a single day of downtime will have a significant financial impact.
Even if it still runs decently, older equipment can often deliver diminishing returns. While it may seem like you’re saving money by avoiding a new purchase, the reality is that:
Newer equipment, on the other hand, can improve output, reduce costs, and generate a stronger return over time.
Outdated equipment may also hold your business back from taking on new work. You might have to pass on opportunities because you don’t have the capacity or equipment to deliver a request within the required timelines.
This is one of the most overlooked costs of delaying upgrades: the opportunities you never get to pursue.
BLOG: Unlocking Growth with Data-informed Financing
Equipment failures create safety hazards for your team and others. In some cases, this can lead to workplace injuries, insurance claims, and regulatory penalties—all of them costly.
Investing in newer, safer equipment helps reduce these risks and protects your business.
If the downsides are so clear, why do so many businesses wait?
The most common reason is simple: cash flow concerns.
Large equipment purchases often feel like a major financial burden even when they’re desperately needed. The pressure can feel especially heavy when you’re balancing payroll, materials, and other operating expenses.
But this is where equipment financing changes the equation.
Instead of paying for equipment upfront, financing allows you to spread the cost over time. This helps make equipment upgrades more accessible and manageable. Here’s how it helps:
You don’t have to tie up cash that could be used for other priorities. This keeps your business flexible and prepared for unexpected expenses or opportunities.
With the right financing structure, your payments will align with your cash flow whether that means seasonal payments, step plans, or deferred starts.
Financing allows you to act based on business needs, not just available cash. This means you can replace underperforming equipment before it starts costing you more than it’s worth.
Depending on your situation, equipment purchases may qualify for tax advantages like Section 179 deductions, allowing you to expense the cost of equipment in the year it’s placed into service.
At Team Financial Group, we understand that equipment upgrades are about positioning your business for growth. We work with business owners to create financing solutions that make sense for their operations, goals, and timelines.
Here’s what you can expect when you work with us:
We offer a range of solutions, including:
We know timing matters. Our streamlined process allows for quick approval, so you can move forward without delays.
We take the time to understand your needs and evaluate your options. Whether you’re upgrading a single piece of equipment or planning a larger investment, we’re here to support you.
BLOG: How to Create an Equipment Budget Built for Long-term Growth
Delaying equipment upgrades might seem like a way to save money but in many cases, it does the opposite. Between lost productivity, rising repair costs, downtime, and missed opportunities, the true cost of waiting is often significant.
With a clear plan and the right financing partner, you can take a proactive approach—upgrading your equipment when it makes sense for your business and not just when it becomes unavoidable.
If you’re thinking about your next equipment upgrade, Team Financial Group is here to help. Contact us today to explore your options and build a financing plan that keeps your business moving forward.
Business credit can feel like a moving target. You know it matters when applying for financing, but the details of how it works and how to influence it can be confusing. The good news is that equipment financing can play an important role in strengthening your business credit over time.
At Team Financial Group, we work with companies across a wide range of industries to finance the equipment and vehicles they need to grow. Here’s how equipment financing can affect your business credit, how lenders evaluate creditworthiness, and what you can do to build a stronger credit profile moving forward.
Business credit helps lenders determine how reliably a company has handled its financial obligations in the past. A strong credit profile can make it easier to qualify for financing, often with more favorable terms.
Good business credit can also help you:
But business credit is only one piece of the puzzle. At Team Financial Group, we take a broader view of each business’s financial picture.
Equipment financing can influence your business credit in several ways. And using it responsibly can actually help build a stronger credit profile over time.
For newer businesses, equipment financing can help establish a credit history. Each loan or lease creates a record that demonstrates how your business handles repayment obligations.
Making payments on time and successfully completing financing can positively contribute to your business credit profile.
Payment history is one of the most important factors in any credit evaluation. Making consistent, on-time payments shows lenders that your business can manage debt responsibly.
Even a single equipment loan can demonstrate reliability, while multiple successful financing arrangements can strengthen your overall credit profile.
Lenders often prefer to work with businesses that have successfully handled previous financing. If your company has financed equipment before and maintained strong payment habits, it signals lower risk to future lenders.
This credibility can open the door to additional financing opportunities as your business grows.
Of course, every business must start somewhere. Lacking any sort of previous financing history should not preclude you from that first opportunity, but it might place some limits on the options available.
While credit scores are important, lenders typically look at several different factors when evaluating an equipment loan application.
Understanding these factors can help you better prepare for financing and improve your chances of approval.
Business credit scores are typically generated by credit bureaus such as Dun & Bradstreet, Experian Business, or Equifax Business. These scores often range from 0 to 100 and reflect how consistently your business has paid its financial obligations.
A higher score generally indicates a lower risk to lenders.
However, many small businesses do not have an extensive credit history. In those cases, lenders may also review the owner’s personal credit profile as part of the evaluation.
For smaller or privately owned companies, personal credit can play a role in financing decisions. This is especially common for startups or businesses that have not yet built a long business credit history.
Personal credit helps lenders understand how the business owner has managed financial responsibilities in the past.
Cash flow is one of the most important indicators of whether a business can repay a loan. Lenders want to see that your company generates enough revenue to comfortably cover its expenses and financing payments.
Even if a business has a lower credit score, strong and consistent cash flow can demonstrate the ability to support new financing.
Businesses that have been operating for several years may have an easier time qualifying for financing because they have a longer track record. However, newer companies are not necessarily excluded.
Many lenders, including Team Financial Group, regularly work with newer businesses when the overall financial picture is strong.
In equipment financing, the equipment itself often serves as collateral for the loan. This can reduce the risk for lenders and make it easier for businesses to qualify for financing compared to unsecured loans.
Collateral can also help offset other risk factors, such as a shorter credit history or lower credit score.
One of the most common misconceptions about equipment financing is that only businesses with excellent business credit can qualify. While strong credit certainly helps, it is not always the deciding factor.
At Team Financial Group, we take a flexible approach to evaluating financing applications. We recognize that credit scores do not always tell the full story.
A business with a lower credit score may still qualify if it has:
This comprehensive approach allows us to support businesses that may not meet the more rigid criteria of traditional banks.
BLOG: 7 Equipment Financing Myths Debunked
Even if your business credit is already in good shape, there are always ways to further strengthen it. Improving your credit profile can increase your financing options and position your business for long-term growth.
Consistent, on-time payments are the single most effective way to improve your credit. Late payments can quickly damage your credit profile, while steady payment history builds credibility with lenders.
Business credit reports sometimes contain errors or outdated information. Reviewing your reports regularly allows you to catch and correct any inaccuracies before they impact a financing decision.
Strong cash flow not only helps your business operate smoothly but also reassures lenders that you can handle financing obligations. Keeping detailed financial records and maintaining positive cash flow can strengthen your loan applications.
Taking on too much debt at once can negatively affect your credit profile. Strategic financing that is focused on investments that generate revenue can help you grow without placing unnecessary strain on your finances.
BLOG: Cap Ex Spending and Planning Ahead
Working with experienced lenders who understand your business can make a significant difference. Long-term financing relationships can lead to faster approvals, better terms, and more flexible options as your company grows.
BLOG: Top Considerations for Choosing the Right Equipment Financing Partner
At Team Financial Group, we understand that every business has a unique financial story. Our goal is to understand all the factors surrounding your business and how equipment financing can support your growth.
We work with business owners to create customized financing solutions that align with their goals, cash flow, and operational needs.
Our approach includes:
Whether you are expanding your operations, replacing aging equipment, or investing in new technology, we aim to make the financing process as simple and supportive as possible.
BLOG: How Easy Equipment Financing Helps Grow Your Business
Equipment financing is a path to new tools or vehicles—it can also help strengthen your company’s financial foundation. By making consistent payments and managing financing responsibly, you can build a credit profile that supports future opportunities.
If you are considering equipment financing and want to explore your options, contact the lending specialists at Team Financial Group. Our team is happy to discuss your situation, answer your questions, and work with you to find a financing solution that supports your success.
Seasonal shifts in revenue are part of the job for most construction companies. Business booms in warmer months, then slows down during winter or rainy seasons. But even when projects pause, expenses like payroll, equipment costs, insurance, and overhead keep coming.
That’s why smart construction companies use financing to smooth out the highs and lows, preserve working capital, and position themselves for long-term growth. With the right strategy and financing partner, your organization can weather the slower seasons without missing a beat.
At Team Financial Group, we understand the unique cash flow management challenges of the construction industry. We work with contractors, builders, and trades across the country to create customized financing solutions that fit their seasons, projects, and goals.
Here’s how your construction company can use financing to improve seasonal cash flow—and how we can help.
Cash flow in construction is often unpredictable.
You might be forced to deal with delayed payments, up-front material costs, equipment breakdowns, labor shortages, and tight margins. Add in slowdowns from weather or project cycles and the financial pressure can build quickly.
Some of the biggest causes of cash flow issues in construction include:
This variability can make it difficult to plan ahead, pay your team consistently, or invest in new equipment when you need it.
That’s where flexible financing comes in.
BLOG: 7 Equipment Financing Myths Debunked
When used strategically, financing is a tool that can help your construction company:
Here are a few ways that construction companies can use financing to stay ahead:
Heavy equipment purchases can tie up capital that you need for payroll, materials, or marketing campaigns. Financing purchases helps spread out the costs over time, turning a large upfront hit into more manageable monthly payments.
And when you work with a lender like Team Financial Group, you may qualify for 100% financing, meaning no down payment is required. This can open you up to:
Bonus: Certain heavy equipment that is financed and placed into service before year-end may qualify for Section 179 tax deductions, which offer immediate savings.
We understand that construction revenue isn’t always steady or predictable. That’s why we offer custom payment structures, including:
These options give you breathing room when you need it most without putting your cash flow at risk.
If you don’t need to own equipment in the long term, then leasing can be a smart alternative. This is especially helpful if:
We offer lease options like Fair Market Value (FMV) leases or $1 buyout leases that let you choose the right path for your business: own or return.
Sometimes it’s less about your equipment and more about cash on hand. Working capital financing can help cover:
BLOG: How Much Working Capital Do I Need for My Business?
Let’s say a Michigan-based construction firm has a strong spring–fall season, but winter projects are limited. They need a new skid steer and want to hold onto cash for payroll and marketing.
Instead of paying $60,000 up front, they could work with Team Financial Group to:
The business stays operational and ready during the off-season, and is also positioned to take on new work when spring arrives.
We’re not a big bank and we don’t believe in one-size-fits-all financing. We know construction companies need speed, flexibility, and common-sense solutions to grow. Here’s how we can help.
We know time is money. Our approvals are quick (often within 24 hours), and we don’t bury you in red tape.
We work alongside you to tailor each loan or lease to your revenue cycles, equipment needs, and growth plans.
From seasonal payments to deferred starts, we make sure your financing works for you with as few hurdles as possible.
We’re in it for the long haul. Whether you need a single piece of equipment or a long-term financing partner, we’re here to support your success.
BLOG: How to Create an Equipment Budget Built for Long-Term Growth
Construction companies face enough challenges—you shouldn’t have to worry about cash flow on top of everything else. With a smart financing solution from Team Financial Group, you can manage seasonality, invest in growth, and keep your business moving forward no matter the time of year.
SUCCESS STORY: RGD Builders Receives a Financing Option Built for Their Business
Contact us today or call 616-735-2393 to talk with a real person about how we can help with your equipment or working capital needs.
When your business needs new equipment, you often need it fast. But unless you’re paying cash for big items, securing an equipment loan is usually the first step.
That can bring up a big question: What do lenders actually look for in an equipment loan application?
At Team Financial Group, we can help business owners secure the equipment financing you need to grow, compete, and move forward. While every lender will have different specific requirements, there are some common factors that most look at when evaluating a loan application.
Let’s discuss the typical equipment loan requirements, how to strengthen your chances of approval, and why Team Financial Group may be a better fit for your business than traditional lenders—especially if you’re facing unique challenges or opportunities.
RELATED: How to Navigate an Equipment Financing Application
Lenders look at a variety of financial and operational indicators to determine whether a business is likely to repay the loan. But not all lenders evaluate these factors in the same way.
Traditional banks tend to rely on strict formulas and rigid credit thresholds. That can make it difficult for small or growing businesses—especially those without perfect credit histories—to get approved.
At Team Financial Group, we take a more open-minded, relationship-driven approach. We believe that businesses can have potential beyond their numbers, and we work to find creative financing solutions at times when others might say no.
Still, knowing what most lenders evaluate can help you strengthen your application and improve your chances of approval, whether you’re applying with us or anyone else.
Most lenders prefer to work with businesses that have been operating for at least one to two years.
That said, newer businesses often aren’t automatically disqualified. For example, we’ve helped many startups and young businesses get the equipment they need to hit the ground running.
Tip: If you’re a newer business, be ready to share a clear business plan, detailed projections, and your own industry experience to build lender confidence.
RELATED: How to Create an Equipment Budget Built for Long-term Growth
Both your business credit score and personal credit score may come into play, especially if you’re a small business or sole proprietor.
Tip: Always check your credit reports ahead of time so you can address any errors or prepare to explain past issues.
Lenders want to see that your business generates enough revenue to cover loan payments. Key documents often include:
We use this information to understand your financial health and determine an affordable monthly payment.
Tip: Keep your books organized and up to date. Clean, accurate financials can significantly boost your chances of approval.
This ratio shows how easily your business can repay debt using its operating income. A DSCR of 1.25 or higher is often preferred by traditional lenders, meaning you make $1.25 for every $1.00 of debt.
At Team Financial Group, we take a more holistic view. If your DSCR is lower due to temporary cash flow constraints or a recent investment in growth, we’re still happy to talk through potential options.
Lenders will ask for details about the equipment you want to finance, such as:
We’ll want to understand how the equipment supports your business and generates ROI.
Tip: Include a quote or invoice from the seller, if possible. It helps speed up the process.
Some lenders require a down payment—typically 10–20%—especially for used equipment or businesses with lower credit. But at Team Financial Group, we can sometimes offer 100% financing with no money down, depending on the deal.
RELATED: $1 Buyout Lease vs. FMV Lease: What’s the Difference?
Many equipment loans are self-collateralized, meaning the equipment you’re purchasing serves as the collateral. This reduces risk for the lender and can help you get approved with better terms.
Tip: If you’re purchasing highly specialized or niche equipment, be ready to explain its resale value or importance to your business operations.
If you want to increase your chances of approval and potentially secure better rates and terms, here are a few ways to prepare:
Have the right paperwork ready so you can move your application forward quickly and show that you’re running a financially responsible business.
Help lenders understand how this equipment will improve your business, whether it reduces costs, boosts output, or increases revenue.
If you’ve had credit issues, tax problems, or a rough patch, don’t hide it. Good lenders appreciate transparency, especially when you can show how you’ve recovered.
This might be the most important factor of all. The lender you choose can make or break your experience.
At Team Financial Group, we specialize in commercial equipment financing that has helped a wide variety of businesses. We also often do things differently than traditional lenders.
We take the time to understand your business, your goals, and your needs. We want to know what you’re aiming to achieve.
Need a decision quickly? We have approved and funded some loans in less than 24 hours. When you’re ready to grow, we’re ready to move.
From seasonal payments to $0 down financing, we can tailor loans to match your cash flow and business model.
Startups, private-party sales, or used equipment are not immediate deal-breakers. We’ll explore creative possibilities that may make your equipment loan work for you and us.
RELATED: 7 Equipment Financing Myths Debunked
If you’ve reviewed the equipment loan requirements but want a financing partner with more flexibility than a bank, Team Financial Group is here to help.
You can start your application online in just a few minutes, or give us a call to talk through your options. We’re happy to answer your questions and find a solution that supports your business.
Contact us today or call 616-735-2393 to speak with an equipment financing expert.
If you sell equipment, you already know that cost is one of the biggest hurdles in closing deals. Even when potential customers love your product, sticker shock can derail the conversation fast—especially for capital-intensive equipment purchases.
But what if you could take the price conversation off the table?
Vendor financing can offer your customers easy, flexible financing at the point of sale. You can remove a major barrier to purchase, close more deals, and build longer-lasting customer relationships.
At Team Financial Group, we specialize in creating fast, reliable vendor financing programs tailored to your business and your customers. Let’s break down the benefits of vendor financing, how it works, and how partnering with us can help grow your sales pipeline without increasing your risk.
Vendor financing is a strategic partnership between an equipment vendor (you) and a third-party lender (like Team Financial Group). Instead of sending customers away with the burden of securing their own financing, you can offer financing options directly at the point of sale.
The customer gets the equipment they need without a large upfront payment. You get to close the sale faster, with fewer objections.
BLOG: 7 Equipment Financing Myths Debunked
Offering a financing option is all about removing the financial friction that slows down buying decisions. Here’s why vendor financing is such a powerful sales tool:
Instead of facing a large capital expense, your customers can make manageable monthly payments that fit their budget. This opens the door to:
When you eliminate the need for external financing research and paperwork, your deals move faster. Team Financial Group can often approve and fund deals within 24 hours, so you don’t have to wait weeks for your customer to find financing on their own.
Most equipment buyers are already planning to finance. But if you don’t offer an appealing financing solution, they may walk away. By providing a clear path to ownership with no need for a third-party bank, you reduce drop-off and increase conversions.
Customers appreciate a seamless buying experience. When you offer flexible, affordable financing through a trusted partner, it reflects positively on your business and encourages customers to return the next time they need financing.
Vendor financing doesn’t just benefit your sales process. It also brings big advantages to your customers:
The result? More satisfied customers who feel confident in their investment and your business.
We work closely with vendors to build customized financing programs that help you win more business. Here’s what sets us apart:
We know your customers are ready to move fast. That’s why we offer:
Every business is different, and we don’t believe in one-size-fits-all contracts. Depending on the circumstances, we can offer:
We make it easy for vendors to integrate financing into their sales process. You don’t have to act as a bank. We can handle the financing while you stay focused on selling equipment.
From construction equipment dealers to agricultural suppliers and manufacturing technology, we’ve built long-term relationships with vendors who trust us to treat their customers with respect and urgency.
BLOG: Top Considerations for Choosing the Right Equipment Financing Partner
Here are some answers to common questions from equipment vendors:
Q: Do I have to take on any financial risk?
A: No. Team Financial Group can provide financing directly to your customer. You’re paid in full once the deal is funded. We handle collections and risk on our end.
Q: How quickly can my customer get approved?
A: In many cases, we can approve and fund deals in less than 24 hours, especially for well-qualified customers. Our team is built for speed and service.
Q: Is there a cost to set up a vendor program?
A: No. There is no cost to you for setting up a vendor relationship with Team Financial Group. We partner with vendors as a value-add to support your sales.
Q: What types of equipment can be financed?
A: Just about anything your customer uses for business: vehicles, machines, tools, technology, software, and more. We also finance used equipment and private-party sales.
Q: How do I present financing to customers?
A: We’ll help you with that! Our team can provide training, marketing materials, and payment calculators so you can confidently offer financing as part of your pitch.
At Team Financial Group, we’re passionate about helping vendors grow their business through better financing solutions. We understand that your success depends on your customers’ ability to buy. We’re here to make that easier, faster, and more flexible for everyone.
Whether you’re looking to reduce customer drop-off, shorten your sales cycle, or simply offer more value, vendor financing is one of the most powerful tools you can use.
Call us at 616-735-2393 to speak with a vendor financing specialist. We’ll help you turn more quotes into closed deals.